A fast close begins before the offer is accepted.
Closing quickly is not simply a matter of choosing an aggressive date. The seller, buyer, agents, lender, escrow, title, and other professionals must be prepared to complete their responsibilities on a compressed calendar.
A seller can help by gathering property records, loan information, disclosures, improvement documents, HOA materials when applicable, and the details needed to answer likely questions before they become delays.
Offer quality matters as much as the timeline.
A proposed closing date is useful only when the buyer has a credible path to perform. Financing preparation, proof of funds, contingency structure, appraisal exposure, deposit timing, and the responsiveness of the buyer's team all deserve careful review.
The right comparison is not simply the shortest calendar. Sellers should consider net proceeds, certainty, risk, possession, and how each term supports their priorities.
Communication must be immediate and organized.
A compressed escrow leaves less room for missed messages or incomplete information. Clear responsibility for disclosures, access, inspections, lender requests, repair discussions, signing, and final walkthrough helps keep the transaction moving.
Fast does not mean careless. Buyers retain the rights and investigations provided by the contract, and sellers should work with the appropriate real-estate, escrow, legal, tax, and other professionals for their circumstances.
A verified 15-day closing in Northridge.
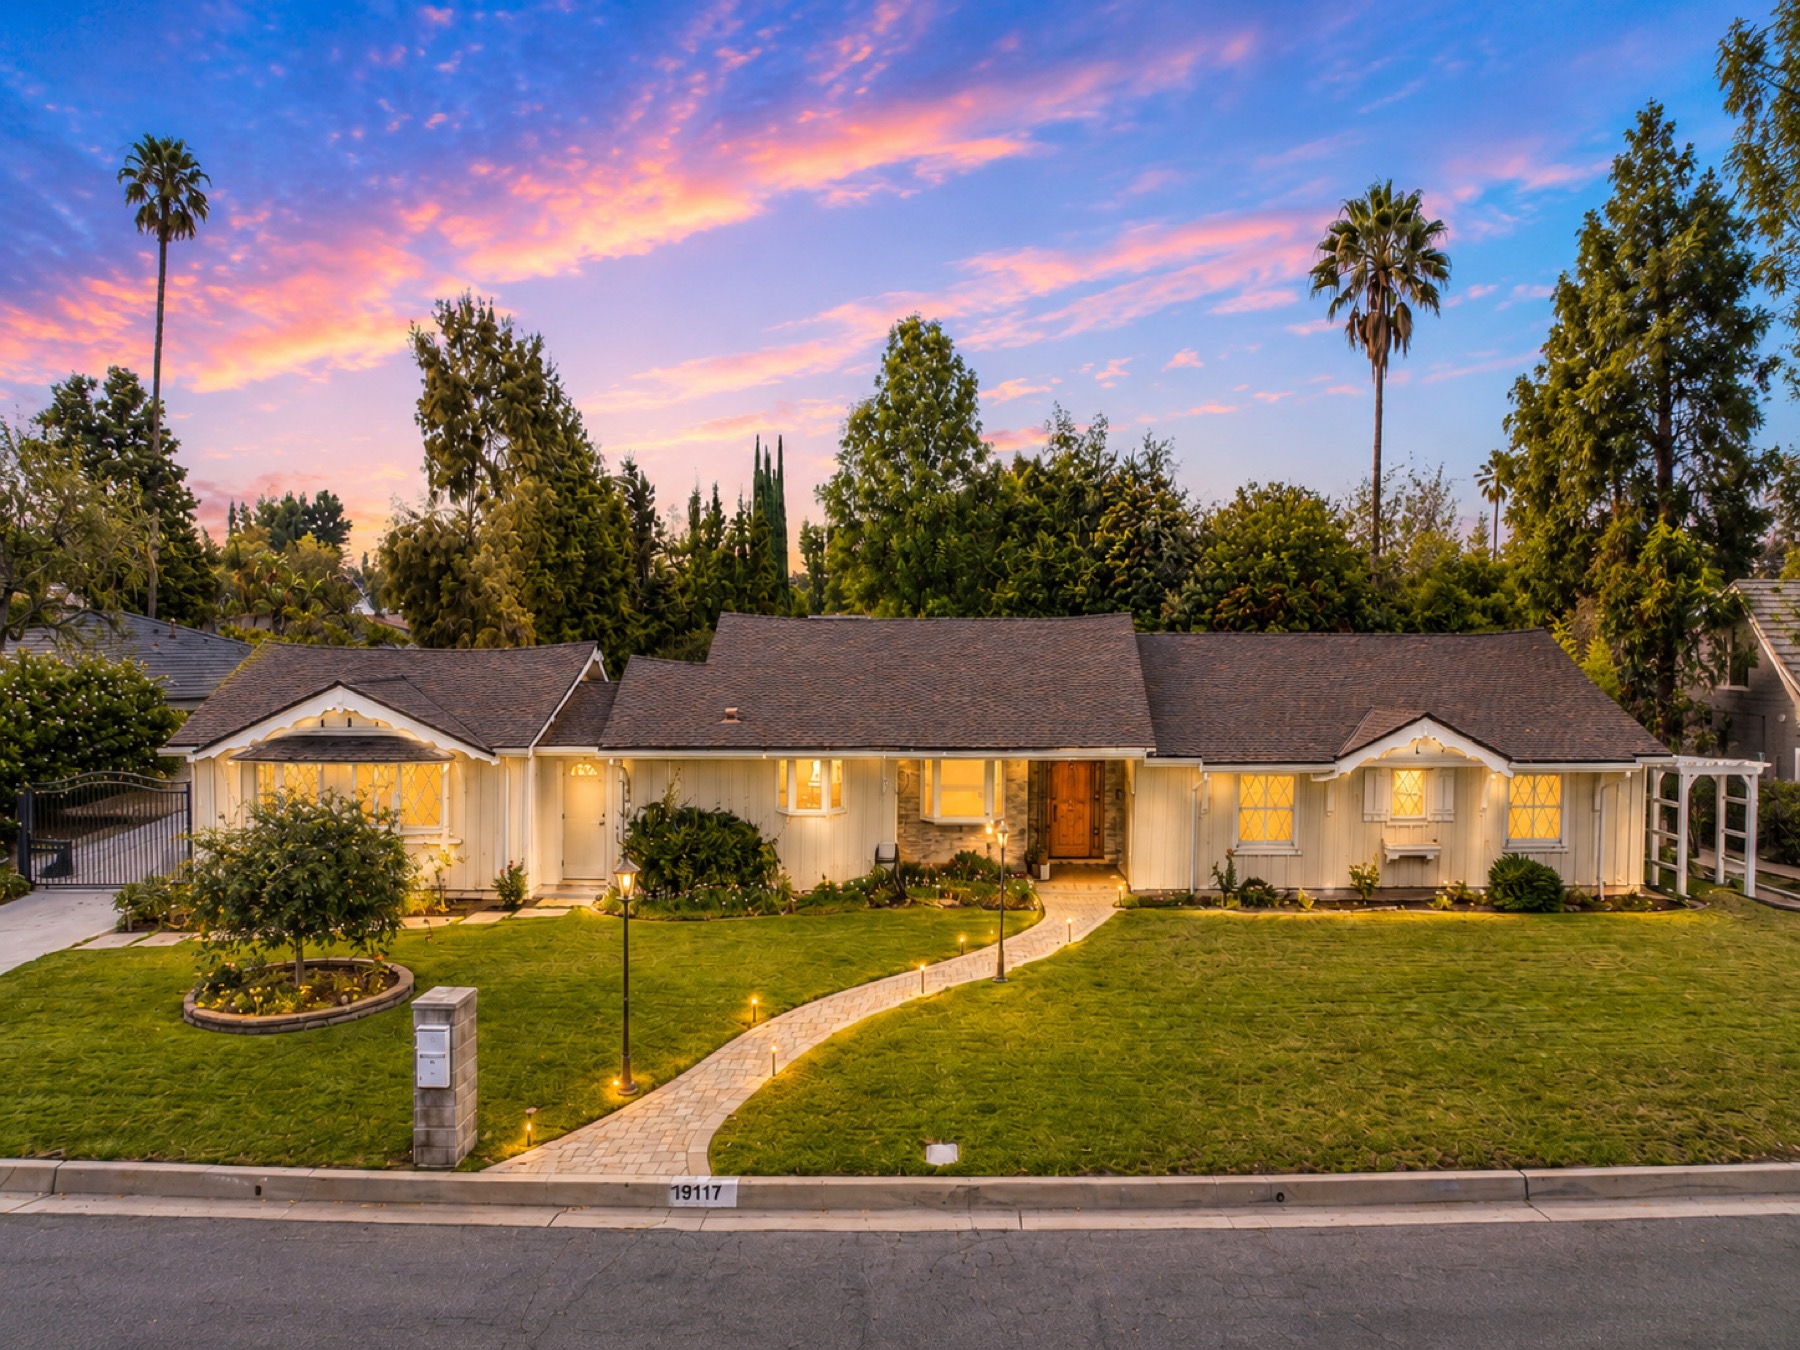
Elliot's sale of 19117 Marilla Street closed on November 13, 2026 for $1,380,000 after a 15-day escrow. The remodeled single-story home offered four bedrooms, three bathrooms, and an official 2,373 square feet.
The result is a useful example of what coordinated transaction management can accomplish. It is not a promise that every property or buyer can close on the same timetable; financing, disclosures, investigations, title, property condition, and individual contract terms can change the schedule.
A seller checklist for a possible fast close.
- Gather loan, title, property, improvement, and HOA information early.
- Complete disclosures thoughtfully and respond promptly to follow-up questions.
- Compare the buyer's financing, proof of funds, contingencies, and team readiness.
- Confirm that escrow, title, lender, and signing logistics can support the proposed date.
- Plan moving, possession, utilities, insurance, and final property access before acceptance.
- Choose the timeline that best balances the seller's outcome, certainty, and practical needs.
This article provides general real-estate information, not legal, tax, financial, insurance, or inspection advice. Consult the appropriate professionals regarding your circumstances.